
A published rate vs. a custom quote
Quiq's own pricing page makes an unusually direct argument: outcome based pricing, it says, creates ambiguity and vendor negotiation over what counts as a "successful outcome." Fini is built the opposite way, one flat number tied to a specific outcome, with a guarantee attached if that outcome comes up short.
Both companies serve regulated industries, and both publish some version of a resolution number. This comparison walks through what each number actually means for a buyer sizing a real deployment.
In this comparison: What each is · How they differ · Capabilities · Feature by feature · Ease of use · What customers say · The full side-by-side · Which to choose · Compliance · FAQ
What is Fini?
Fini is an AI customer-support agent priced per resolution, backed by Y Combinator and Matrix Partners. It connects natively to your helpdesk, knowledge base, CRM, billing, claims, and EHR systems, reaches a 90% resolution rate at 99% accuracy, and is built to go live in 30 days. Across its customer base, Fini handles more than 3 million monthly resolutions in fintech and healthcare. The agent works across voice, chat, and email, answers in 130+ languages, and returns a first response in about five seconds.
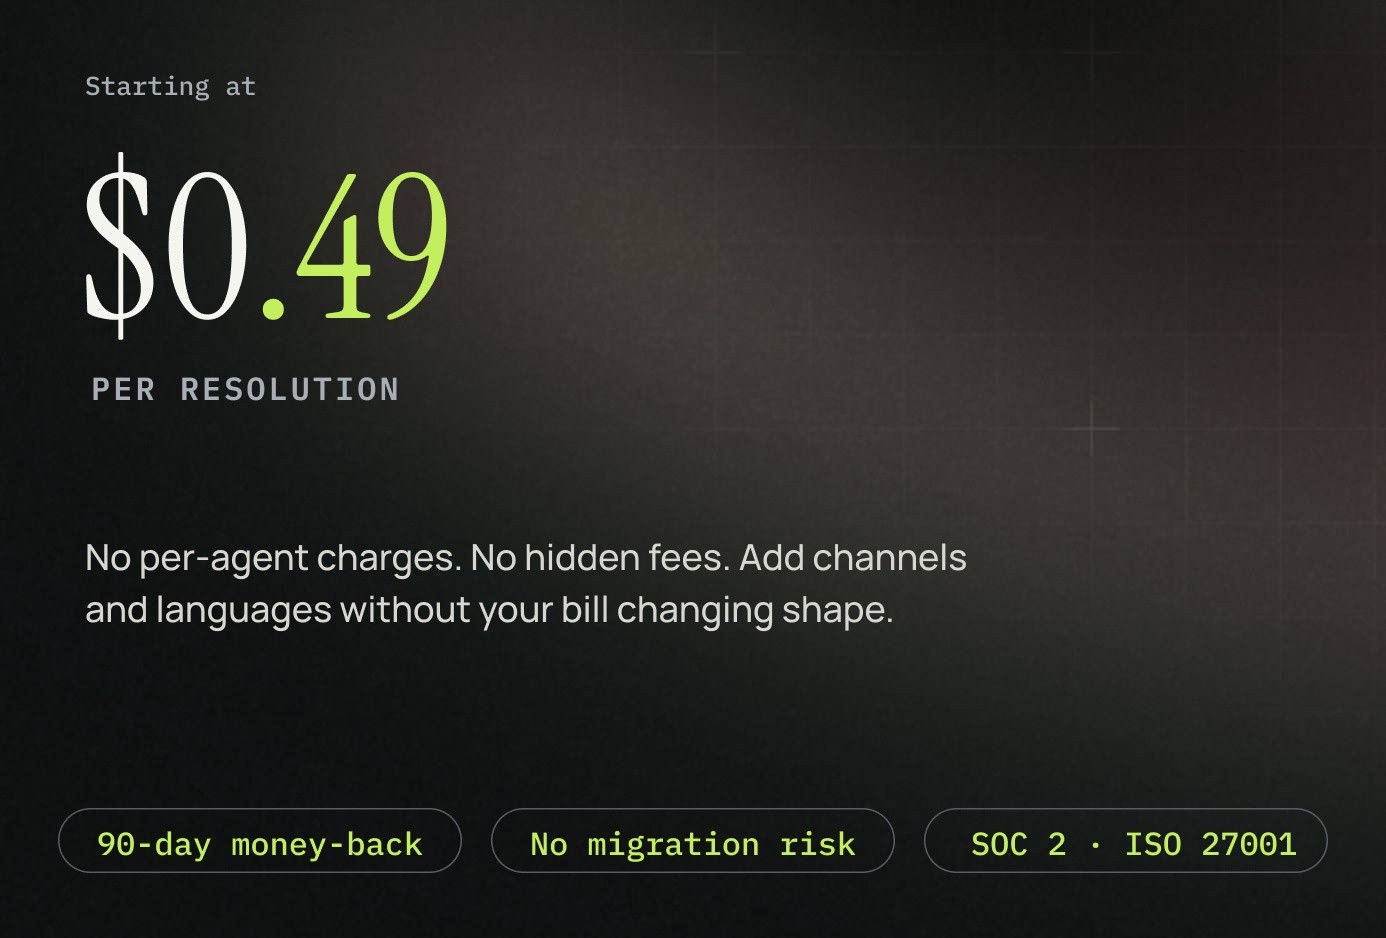
Pricing starts at $0.49 per resolution, with no per-seat fees, so a team can model its own cost from ticket volume alone, before a sales conversation ever starts.
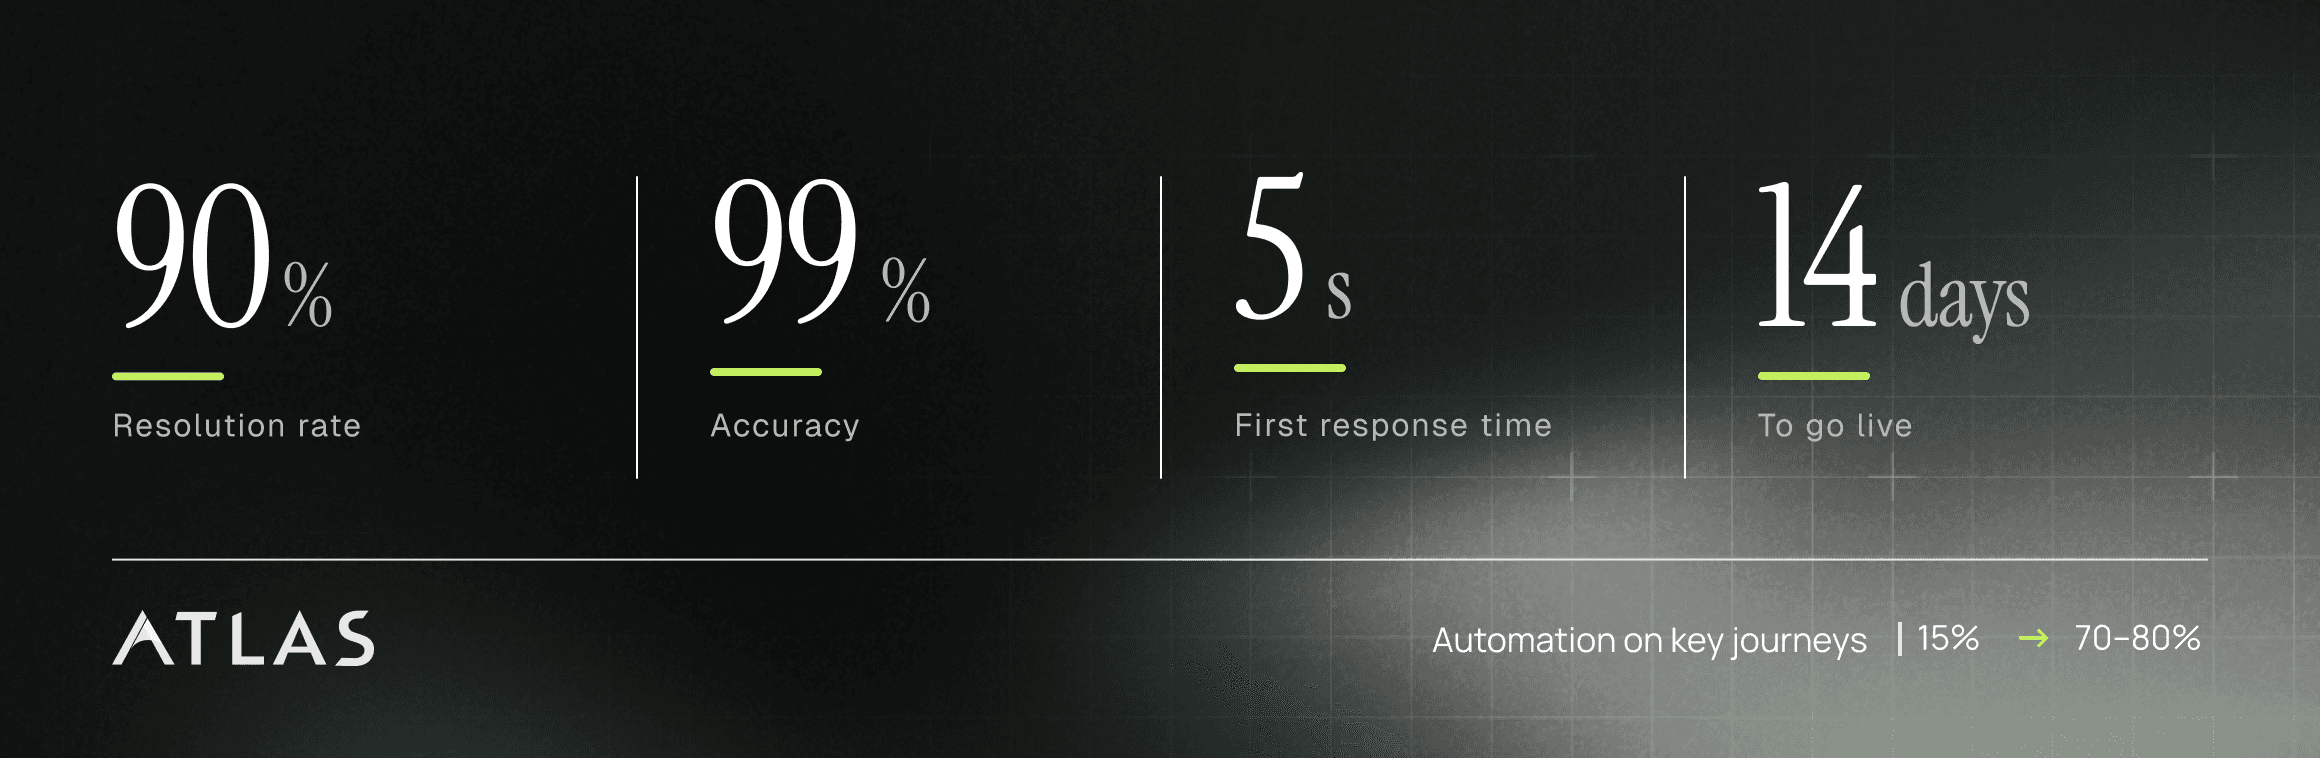
What is Quiq?
Quiq is a Bozeman, Montana based enterprise agentic AI and messaging platform, led by founder and CEO Mike Myer. Its product line spans AI Agents for automated resolution, AI Assistants that act as a real time co-pilot for human agents, Voice AI Agents added in May 2026, AI Workflows for process automation, AI Analysts for conversation QA, and a Digital Contact Center that unifies human and AI agents in one workspace. Quiq's positioning leans on governance and control, branded "Verified Intelligence," and it markets itself as no-code, built for business teams rather than engineers.
Quiq's channel stack, SMS, WhatsApp, Google RCS, web chat, Apple Messages, and Instagram, predates the current AI-agent wave, and its AI agents are layered on top of an existing enterprise messaging platform rather than built agent-first. In banking specifically, Quiq names Brex, OppFi, and Rho as logos on its banking industry page, alongside Southern Credit Union, Bilt, Progressive Leasing, and Creative Planning, though only Southern Credit Union and a Midwest credit union mortgage servicer have published, detailed case studies. Brex, OppFi, and Rho appear as logos without a write-up of their own.
Quiq pricing in 2026
Quiq's own pricing page states plainly that rates aren't published, a prospect reaches a number by meeting with a Quiq expert instead. The model is usage based, priced on the conversations an account actually uses rather than seats or feature tiers, with an optional paid add-on for professional managed services. Quiq goes further than simply keeping its number private, it explicitly argues against the alternative: outcome based pricing, its site says, creates ambiguity and vendor negotiation over what counts as a "successful outcome."
Fini publishes the exact model Quiq is arguing against: a single, fixed rate, $0.49 per resolution, with no per-seat fees and a guarantee attached to the outcome itself. See Fini's full pricing breakdown for plan details, add-ons, and a resolution calculator.
What buyers ask | Quiq | Fini |
|---|---|---|
Published price list | ✗, custom quote only | ✓, flat rate |
Price | Not disclosed, usage/conversation based | $0.49 per resolution |
Stated view on outcome-based pricing | Argues against it on its own pricing page | Built entirely around it, with a guarantee attached |
Rate for additional usage | Custom, requires a sales conversation | N/A, flat rate at any volume |
Can you model cost from one number? | No, requires a quote first | Yes |
How Fini and Quiq differ
The two companies take opposite positions on the same question. Quiq's pricing is a custom, usage based quote, and its own site argues that tying payment to a resolution outcome creates disputes over what counts as "successful." Fini's pricing is nothing but that outcome, a starting rate of $0.49 per resolution with a guarantee if the resolution rate falls short.
The two companies also differ in vertical scope and history. Quiq's heritage is broad enterprise messaging across retail, insurance, hospitality, airlines, and banking, with AI agents layered on top of that messaging stack over time. Fini has held a consistent fintech and healthcare focus throughout, with native connections into claims and EHR systems built specifically for those two regulated industries.
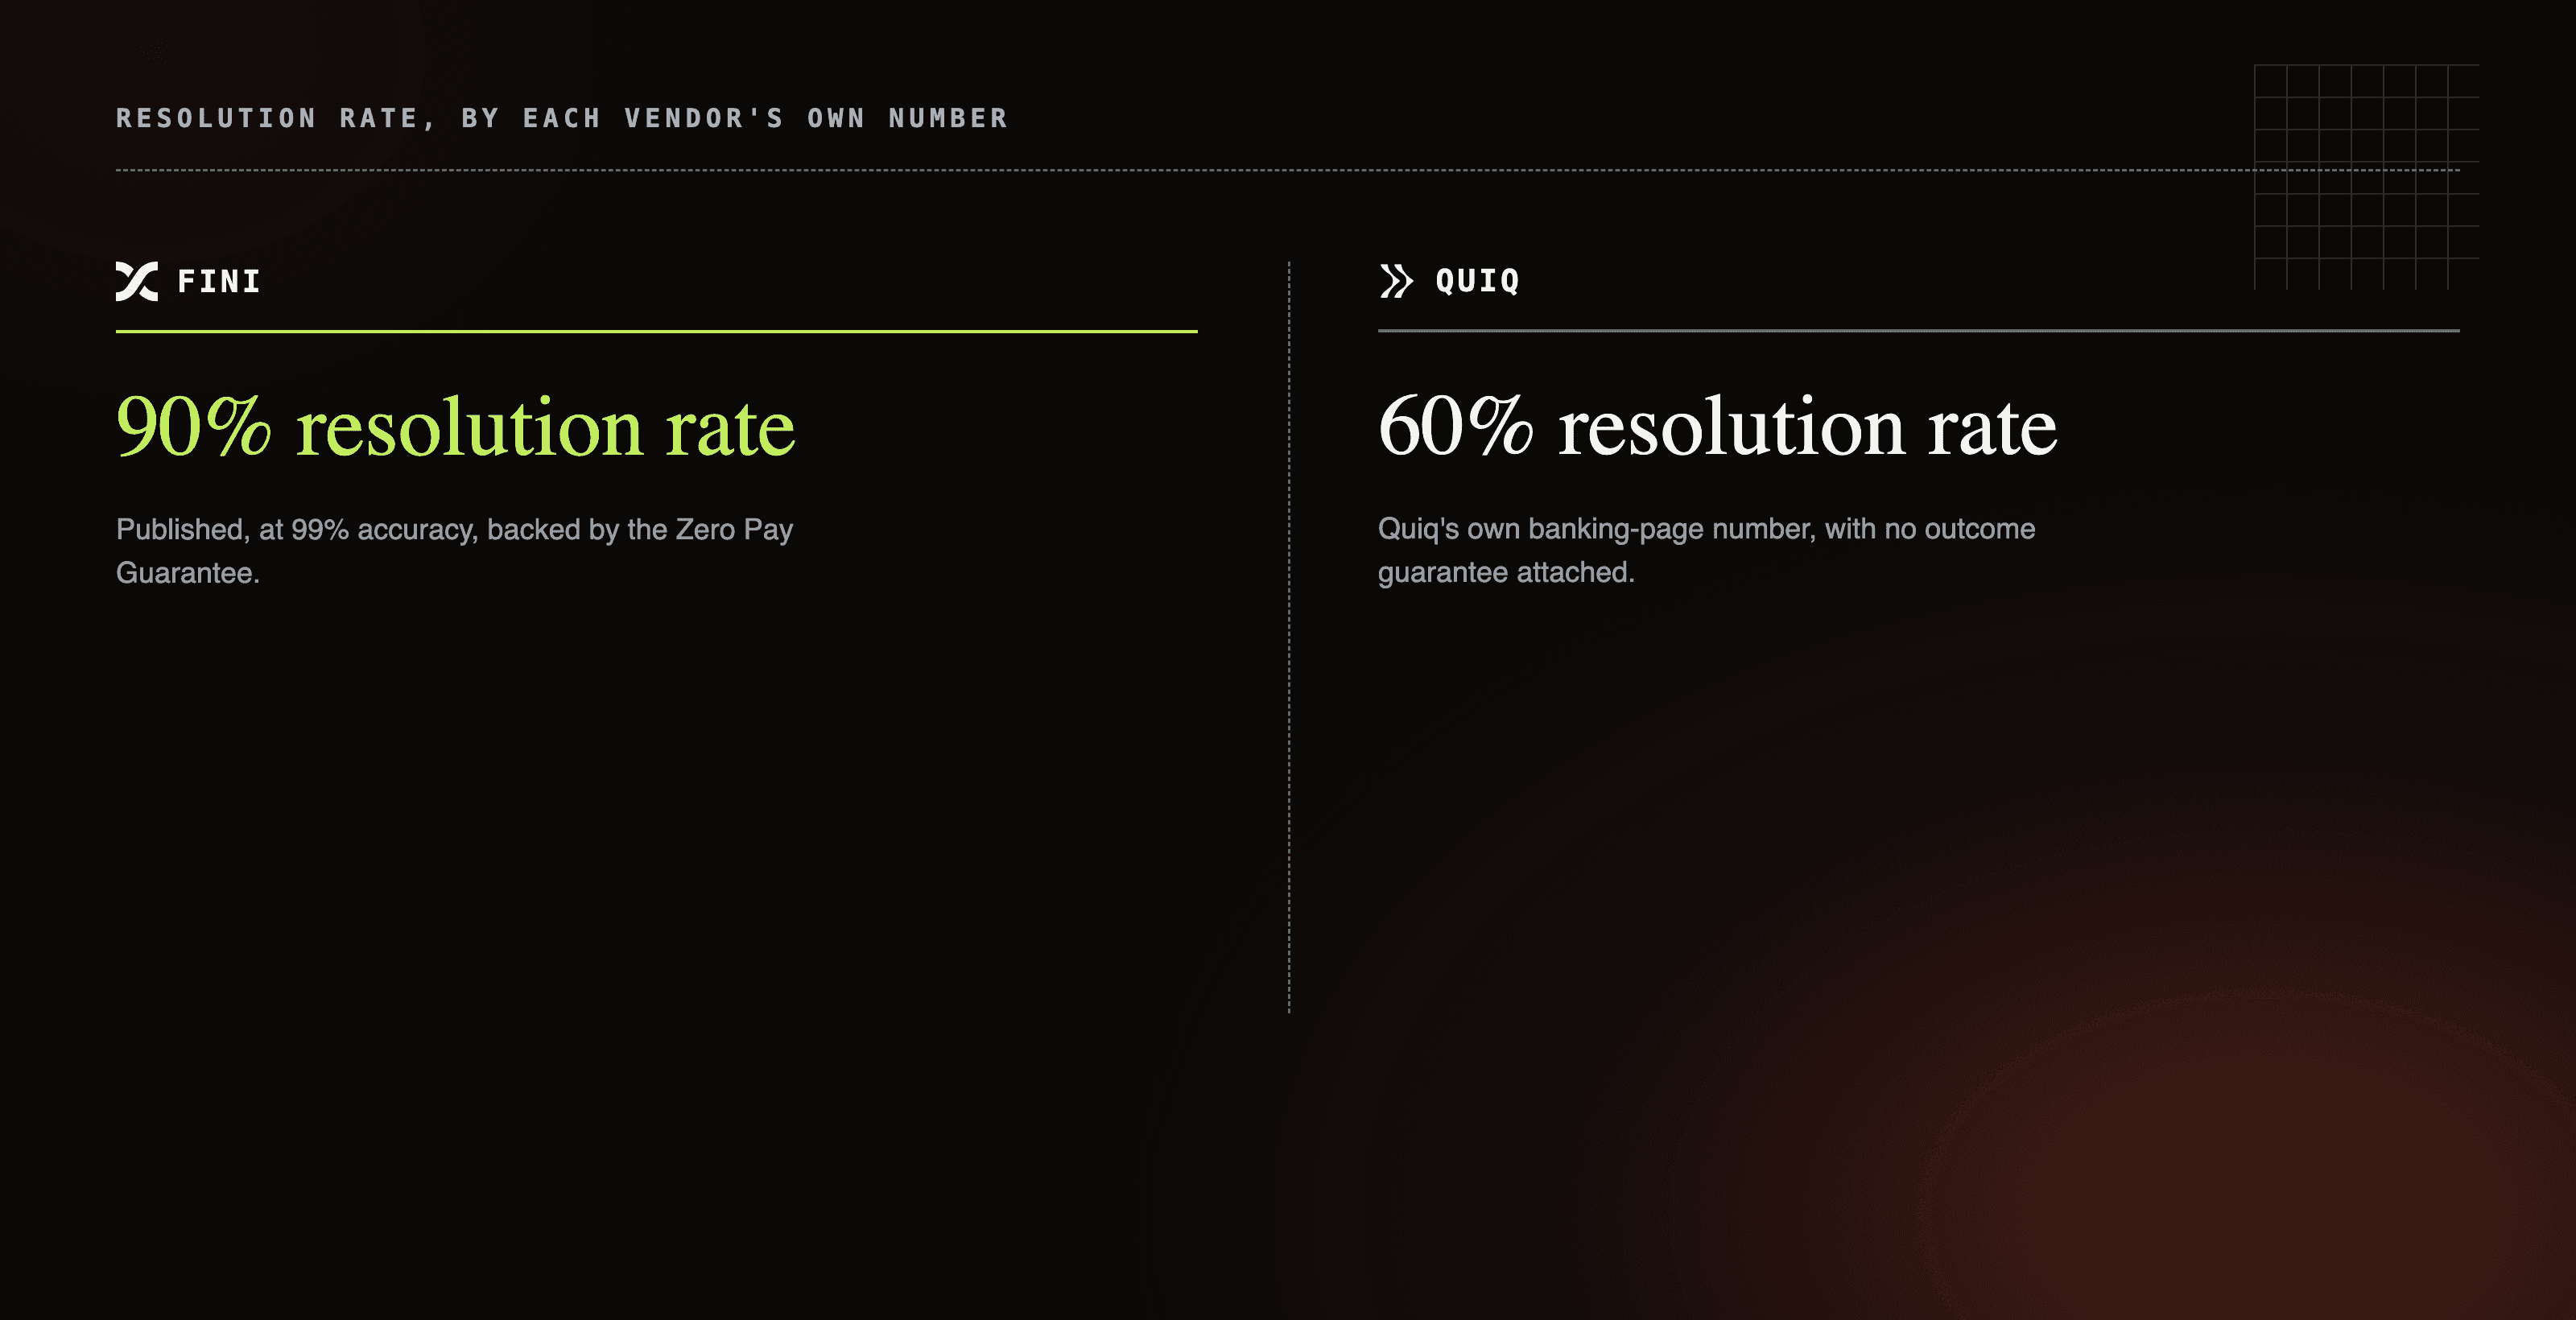
Capabilities side by side
Quiq's platform spans AI Agents, AI Assistants for live agent coaching, Voice AI Agents, AI Workflows for process automation, and AI Analysts for conversation QA, unified inside a Digital Contact Center workspace. Its governance layer, Verified Intelligence, independently checks each AI answer against backend data after generation, runs pre-launch simulations to catch failure modes, and logs every tool call and reasoning step for audit. On its own banking industry page, Quiq states a 60% resolution rate for account holder requests handled without human escalation.
Fini publishes its outcome metric directly instead, a 90% resolution rate at 99% accuracy, and connects natively across helpdesk, CRM, billing, claims, and EHR systems in one connector set, with voice as a native channel alongside chat and email.
Feature by feature
Feature | Fini | Quiq |
|---|---|---|
Channels | Voice, chat, email | SMS, web chat, WhatsApp, RCS, Apple Messages, Instagram, voice (added May 2026) |
Published resolution rate | ✓, 90% at 99% accuracy | ✓, 60% (banking vertical page) |
Pricing model | $0.49 per resolution | Custom quote, usage/conversation based |
Core banking, EHR, or claims integration | ✓, native | Not named on site, CRM/CCaaS/commerce integrations only |
Published outcome guarantee | ✓ (90-Day Money-Back Guarantee) | None published, site argues against outcome pricing |
Ease of use and admin experience
Quiq positions itself as no-code and business-team operable, with "AI-powered data restructuring" to prepare knowledge bases automatically, a contrast it draws directly against engineering-dependent competitors. Its published case studies show real results: Southern Credit Union reports 6x agent productivity handling messages instead of calls, with 100% of texts logged and synced to Salesforce, and a Midwest credit union mortgage servicer cut application drop-off with compliant two-way SMS. There is no general, company-wide implementation SLA published beyond these specific case studies, though.
Fini's published 30-day, staged go-live is run by a dedicated onboarding team against a fixed timeline that applies to every customer, not just the fastest examples. A verified G2 or Capterra rating could not be independently confirmed for Quiq at the time of this research, buyers should check G2 directly for current rating data.
Fini's differentiators
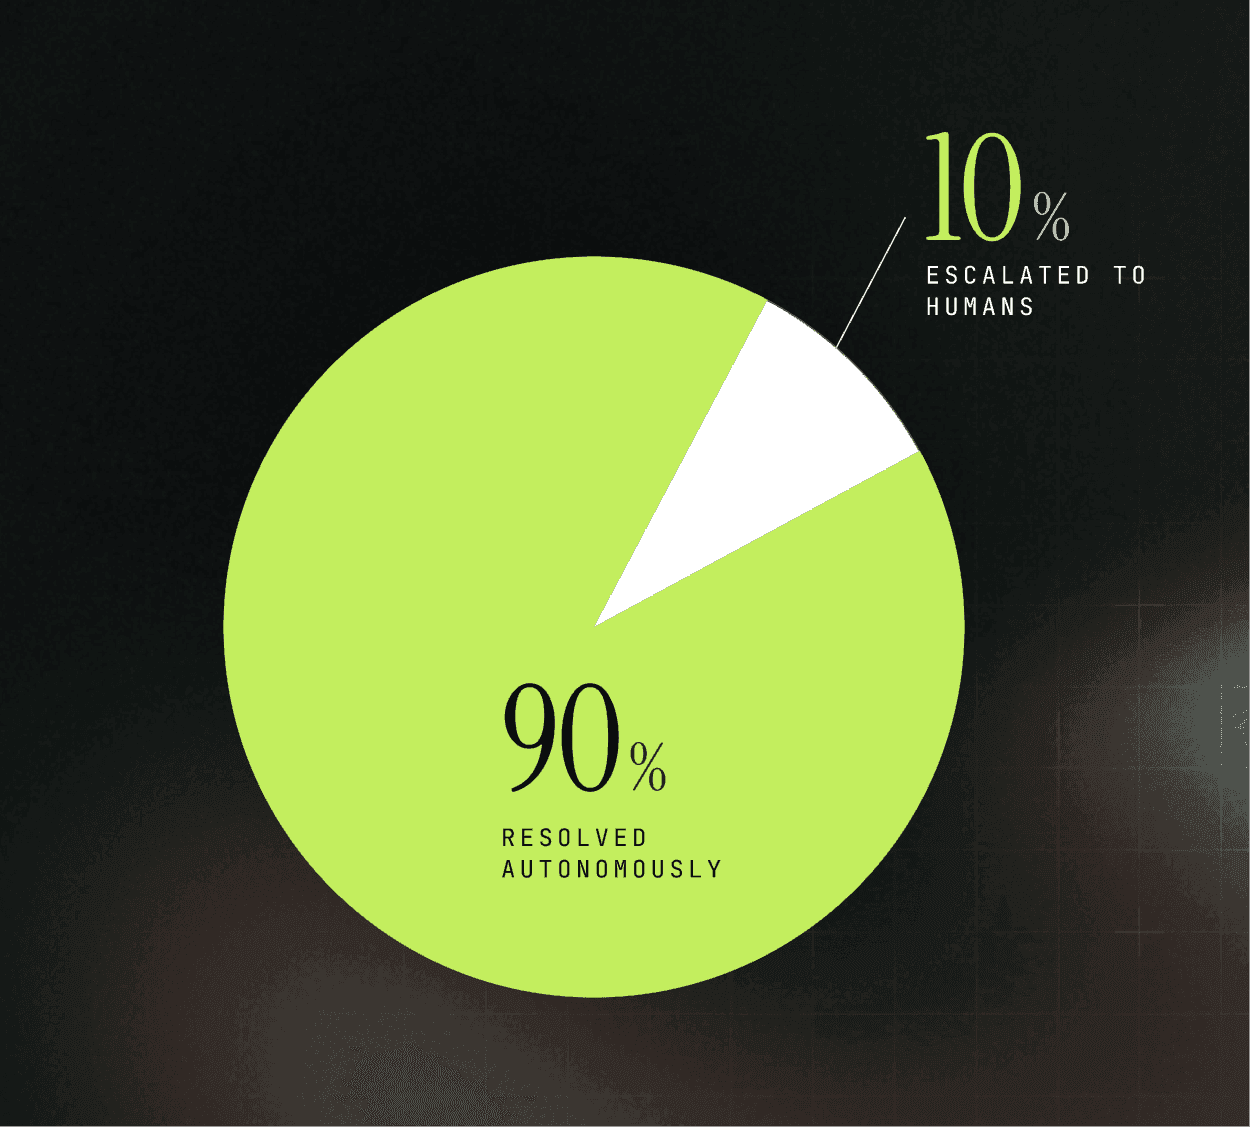
A published rate instead of a custom quote
$0.49 per resolution, starting rate, versus a usage based quote that requires a sales conversation before a buyer sees a number.
A resolution rate you can compare directly
A published 90% resolution rate at 99% accuracy, against Quiq's own 60% figure on its banking page.
An outcome guarantee, not an argument against one
The 90-Day Money-Back Guarantee ties payment to a 90% resolution rate within 90 days, at a publicly quoted rate. Quiq's own pricing page argues the opposite, that tying payment to an outcome creates disputes.
Core system integrations built for two regulated industries
Native connections into claims and EHR systems, where Quiq names CRM, CCaaS, and commerce integrations but no core banking or EHR system anywhere on its own site.
Quiq's recognized strengths
Quiq earns real credit on specific points. Its Verified Intelligence layer, independently cross-checking each AI answer against backend data after generation, running pre-launch simulations, and logging every tool call for audit, is a genuinely detailed governance pitch for regulated buyers. Its channel breadth, spanning SMS, WhatsApp, RCS, Apple Messages, Instagram, and now voice, gives it reach across messaging surfaces most single-purpose resolution bots don't cover. And its published case studies, like Southern Credit Union's 6x productivity gain and a Midwest mortgage servicer's compliant SMS rollout, are detailed, credit-union-specific write-ups with real named results, not just logos.
What customers say
Quiq names Brex, OppFi, and Rho as logos on its banking industry page, but no dedicated case study for any of the three could be found, and none of them appear on Quiq's general customer index either. Its detailed, credit-union-focused case studies are Southern Credit Union, which reports 6x agent productivity and 100% of texts logged and synced to Salesforce, and an unnamed Midwest credit union mortgage servicer, which cut application drop-off with compliant two-way SMS. A verified G2 or Capterra rating could not be independently confirmed for Quiq at the time of this research.
The full side-by-side
Fini | Quiq | |
|---|---|---|
Pricing | $0.49 per resolution, starting rate | Custom quote, usage/conversation based |
Stance on outcome-based pricing | Built around it, with a guarantee attached | Argues against it on its own pricing page |
Outcome guarantee | 90-Day Money-Back Guarantee, 90% in 90 days | None published |
Resolution rate | 90% at 99% accuracy | 60% (banking vertical, Quiq's own number) |
Go-live | 30 days, staged, every customer | No general SLA published |
Channels | Voice, chat, email | SMS, WhatsApp, RCS, web chat, Apple Messages, Instagram, voice |
Vertical scope | Fintech and healthcare | Broad enterprise, retail to banking, no core-banking/EHR integration named |
Compliance | SOC 2 Type II, ISO 27001, GDPR, HIPAA-BAA-eligible, CCPA under agreement | SOC 2 Type II, HIPAA, GDPR, CCPA, EU AI Act |
Backing | Y Combinator, Matrix Partners | Not disclosed on its own site |
Named customers | 3M+ monthly resolutions across fintech and healthcare | Brex, OppFi, Rho (logos only), Southern Credit Union, credit union mortgage servicer (detailed case studies) |
Which should you choose?
Choose Fini if you want one flat, published per-resolution rate you can model from ticket volume alone, a resolution rate and guarantee stated up front, and coverage across both fintech and healthcare workflows including claims and EHR systems. Choose Quiq if you want the broadest messaging channel footprint in one platform and are comfortable with a custom, usage based quote rather than a flat published rate.
A useful gut check: if your team wants a number to budget against before a sales call, or needs claims and EHR workflows alongside general support, Fini's flat rate and published guarantee are built for exactly that situation. If you specifically want the widest reach across messaging channels like WhatsApp, RCS, and Instagram, and don't mind a custom quote, Quiq's platform is the more relevant comparison. See how Fini also compares against Eltropy and Floatbot, two other platforms serving banking and lending workflows.
Compliance
Fini publishes SOC 2 Type II, ISO 27001:2022, GDPR compliance, HIPAA-compliant BAA-eligible contracting, and CCPA availability under agreement, all listed together in one place. Quiq's own site lists SOC 2 Type II, HIPAA, GDPR, and CCPA compliance, and explicitly claims coverage under the EU AI Act, a certification most competitors don't cite, along with data residency options, encryption in transit and at rest, contractual bans on LLM providers training on customer data, a stateless LLM architecture with no persistence of conversation context between sessions, and 99.999% uptime maintained for 10+ years. Its governance layer, Verified Intelligence, adds independent claim verification, pre-launch simulation testing, and full decision-visibility logging on top of those certifications.
Those certifications sit at the platform level though, applied uniformly across every vertical Quiq serves, retail, insurance, hospitality, airlines, and banking alike, rather than purpose-built for regulated finance and health the way Fini's claims are scoped. A team with a hard requirement to confirm Quiq's rating on G2 or Capterra will need to check directly, no verified rating could be confirmed in this research.
Ready to compare on your own data?
The fastest way to know which platform actually fits your ticket volume and compliance requirements is to run the numbers against your own data rather than a vendor's published averages, or a quote that only arrives after a sales call. See Fini's plans or talk to the team about a side-by-side pilot.
Is Quiq's pricing public?
No. Quiq's pricing page states rates aren't published, a prospect reaches a number through a custom quote based on conversation usage rather than seats or feature tiers. Quiq's site explicitly argues that outcome based pricing like Fini's creates ambiguity over what counts as a "successful outcome." Fini publishes a single flat rate instead, $0.49 per resolution.
Who founded Quiq and where is it based?
Quiq is led by founder and CEO Mike Myer and is headquartered in Bozeman, Montana. A specific founding year was not confirmed in this research and should be checked directly with Quiq before citing one.
How much has Quiq raised?
Quiq's funding and investor details are not disclosed on its own site and could not be independently verified in this research. Fini is backed by Y Combinator and Matrix Partners.
What does Quiq's product line include?
Quiq's platform spans AI Agents, AI Assistants (a real time co-pilot for human agents), Voice AI Agents added in May 2026, AI Workflows, AI Analysts, and a Digital Contact Center that unifies human and AI agents in one workspace.
What resolution rate does Quiq publish?
On its banking industry page, Quiq states a 60% resolution rate for account holder requests resolved without human escalation. Fini publishes a 90% resolution rate at 99% accuracy, backed by the 90-Day Money-Back Guarantee.
Are Brex, OppFi, and Rho Quiq case studies?
No. They appear as logos on Quiq's banking industry page alongside Southern Credit Union, Bilt, Progressive Leasing, and Creative Planning, but no dedicated case study for Brex, OppFi, or Rho was found, and none of the three appear on Quiq's general customer index.
What does Quiq's Verified Intelligence layer do?
Verified Intelligence is Quiq's named governance layer. It independently cross-checks each AI answer against backend data after generation, runs pre-launch multi-turn simulations to catch failure modes, and logs every tool call and reasoning step for audit.
Is Quiq SOC 2 and HIPAA compliant?
Quiq's own site lists SOC 2 Type II, HIPAA, GDPR, and CCPA compliance, and explicitly claims coverage under the EU AI Act. Fini publishes SOC 2 Type II, ISO 27001:2022, GDPR, HIPAA-BAA-eligible contracting, and CCPA together on its own site.
Does Fini offer any guarantee Quiq doesn't?
Yes. Fini's 90-Day Money-Back Guarantee ties payment to results, a 90% resolution rate within 90 days, at a publicly quoted rate. Quiq's own pricing page argues against outcome-based guarantees like this one.
Does Quiq integrate with core banking or EHR systems?
No core banking system or EHR/claims system integration is named on Quiq's site. Its published integrations cover CRM (Salesforce, Zendesk, Oracle Service Cloud, SAP, Microsoft Dynamics 365), CCaaS platforms, and commerce tools like Shopify and Stripe. Fini connects natively to claims and EHR systems as a stated differentiator.