Last Updated:
Deepak Singla
IN this article
Explore how AI support agents enhance customer service by reducing response times and improving efficiency through automation and predictive analytics.
Try tracing one AI-handled dispute from the customer's first message to the final notice. Can your team show the evidence, credit events, and reviewer approval, or just a chat transcript? A Reg E workflow needs a case record you can reconstruct. Start by tying every AI action to its source, timestamp, and policy version, while keeping investigation decisions with people.
TLDR:
Track your standard 10-business-day Reg E investigation clock from notice receipt.
Use AI for Reg E intake and status updates. Keep investigation decisions with human reviewers.
Notify consumers of provisional credit amounts and dates within 2 business days.
Log each AI action with its case ID, policy version, source record, and system result.
Fini shares policies and audit trails across voice, chat, and email.
What Regulation E actually covers
Regulation E protects consumer electronic fund transfers (EFTs) under the Electronic Fund Transfer Act. EFTs electronically instruct a financial institution to debit or credit a consumer account through a computer, telephone, or terminal. Examples include debit card purchases, ACH transfers, and person-to-person (P2P) payments to or from covered consumer accounts.
Coverage generally includes banks, credit unions, and certain nonbank providers serving accounts used primarily for personal, family, or household purposes. Business accounts generally fall outside this scope.
For fintech operators handling debit, ACH, and covered real-time payments, fintech support compliance automation does not remove error-resolution duties. Build your Reg E error resolution AI workflow around the applicable procedures for resolving errors.
What counts as a Reg E error
Section 1005.11(a) lists six transaction-related error categories, plus documentation or clarification requests to determine whether an error occurred:
Unauthorized electronic fund transfers.
Incorrect transfers to or from an account.
Transfers omitted from periodic statements.
Computational or bookkeeping errors involving transfers.
Incorrect amounts received from electronic terminals.
Transfers incorrectly identified on required receipts or statements.
Customers need not allege fraud to trigger review.
Routine balance inquiries, duplicate-record requests for other purposes, and posting checks without an asserted error fall outside these procedures. Train Reg E error resolution AI intake to recognize the customer's claim, including possible-error clarification requests.
Unauthorized vs. authorized: the classification that drives liability
For Reg E error resolution AI intake, record who initiated the payment. The definition of unauthorized EFT requires initiation by someone other than the consumer:
without actual authority to initiate the transfer and from which the consumer receives no benefit
A scammer using stolen credentials differs from a consumer tricked into pressing “send.” Escalate coercion or disputed authority for legal review. When comparing the safest AI support vendors for fintech, assess their classification accuracy.
Misclassification can deny consumer protections or misallocate liability for losses. Require review before rejecting claims. Even an authorized payment can involve another covered error requiring investigation.
Investigation timeframes and the clocks that cannot stop
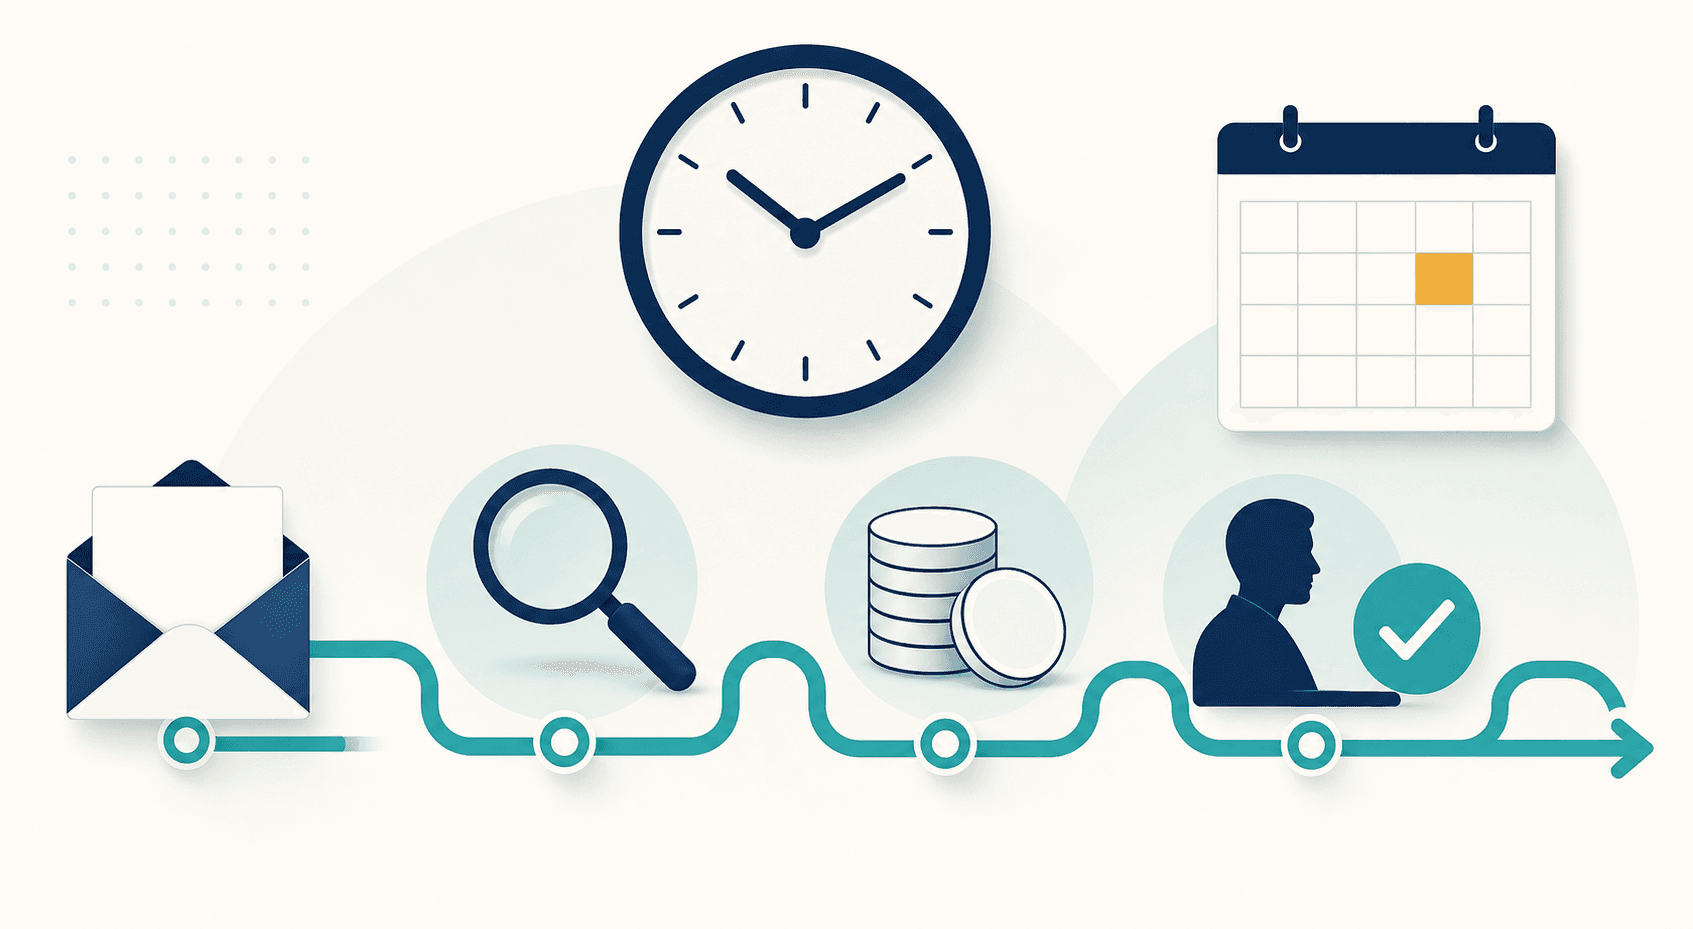
The investigation clock starts when you receive the consumer’s notice of error. Reg E error resolution AI must preserve that receipt date through intake routing.
Applicable window | Deadline from notice |
|---|---|
Standard investigation | Determine error within 10 business days |
Extended investigation | Generally, provisionally credit within 10 business days; finish within 45 calendar days (CFPB § 1005.11(c)(2)) |
Qualifying POS debit or foreign-initiated transfer | Finish within 90 calendar days |
Check the applicable Reg E timeframe exceptions before assigning deadlines. Report results within three business days after completion.
Test controls against the Federal Reserve’s error resolution violation review, which covers 2024 violation data. Assign each approaching deadline an owner.
Provisional credit: rules, reversals, and consumer notice
Extended investigations require provisional credit for the alleged error, including applicable interest, unless a regulatory exception applies. Notify the consumer of the amount and date within two business days; give full use of funds during investigation.
For no error or a different error, provide a written explanation and offer supporting documents. Reverse only unsupported credit, following debit-notice requirements.
The five-business-day protection is not an advance-notice waiting period. After notification, honor covered checks and preauthorized transfers without reversal-related overdraft charges, within the rule’s limits. Require compliance approval before AI agents automate this Reg E error resolution sequence.
Common Reg E violations and examiner findings
The Federal Reserve’s examiner insights on errors and the FDIC’s focus on third-party EFT investigations warrant testing case handling beyond intake.
Use these failure patterns as checkpoints when reviewing Reg E error resolution AI workflows:
Staff delay investigations while waiting for paperwork.
Written notices omit required explanations or document-request rights.
Investigations exclude relevant evidence.
Case classification treats authorization as settling whether an error occurred. An authorized transfer can still involve an incorrect amount.
Test each checkpoint against case records before approving the workflow.
How AI agents handle compliant dispute intake
Reg E error resolution AI intake needs compliance-approved rules. Under § 1005.11(b), oral or written notice must let the institution identify the consumer and account.
Configure intake to capture:
Why the consumer believes an error occurred.
The error type, transaction date, and amount, to the extent possible.
The consumer’s original description for investigator review.
Confirm receipt, provide a case reference, and explain next steps and applicable timelines without promising an outcome. We look for the same discipline in AI for handling refunds, returns, and disputes. Route the case and unresolved questions to a human investigator. Require human review and documented reasoning for investigation determinations.
The audit trail requirement: log AI decisions
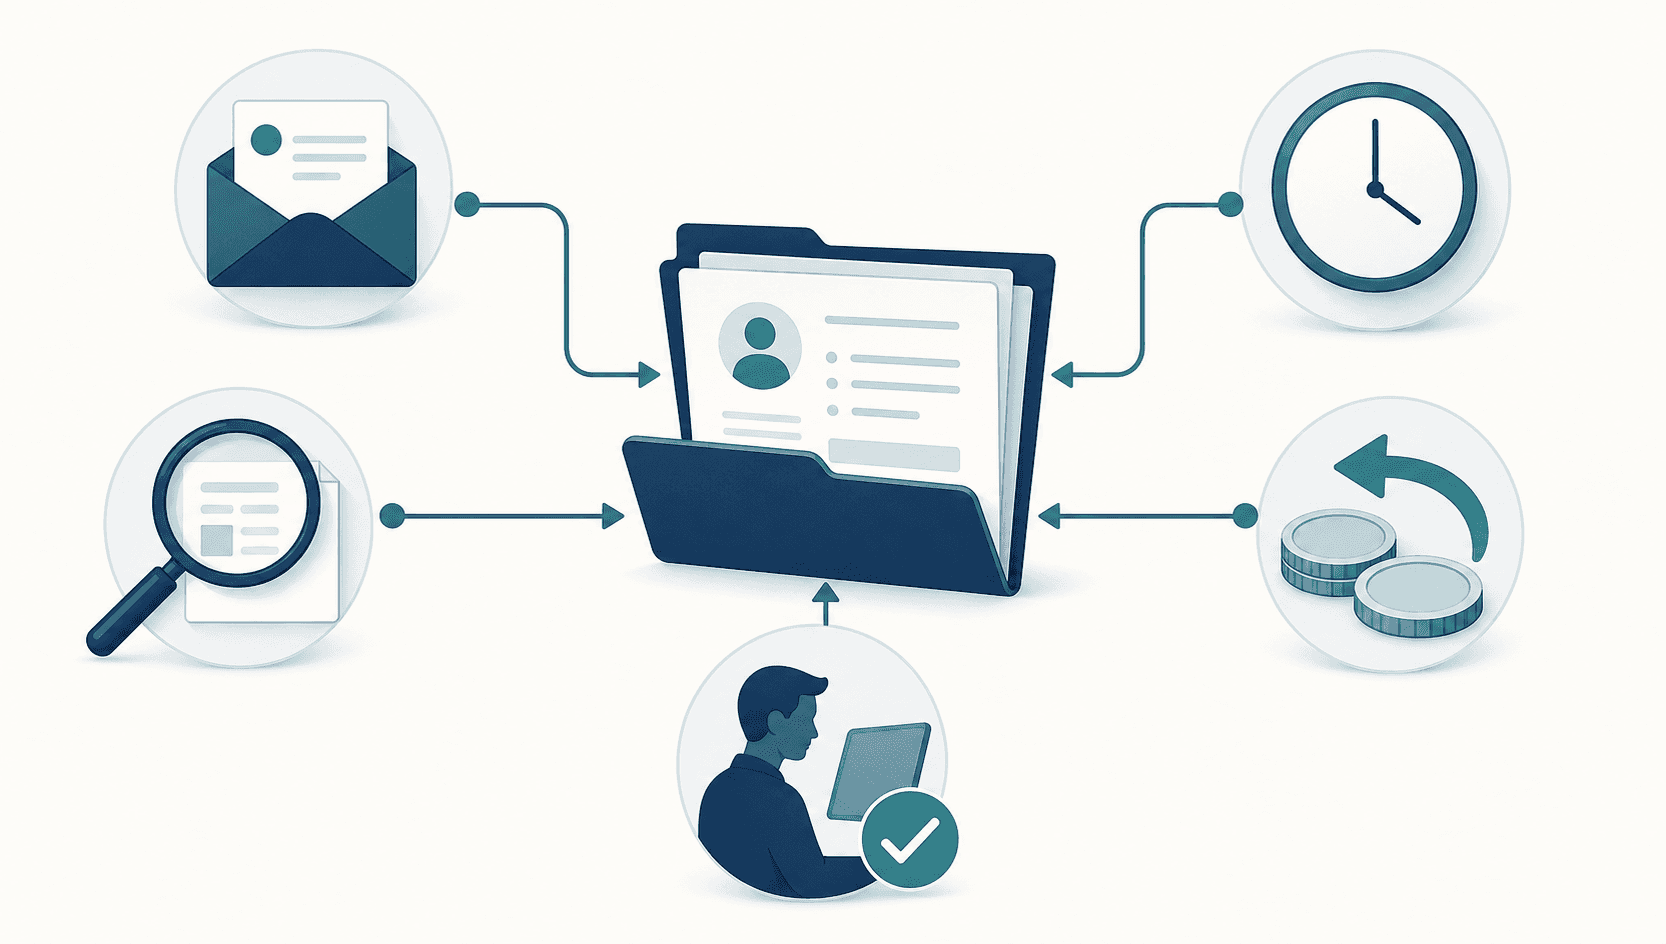
An examiner needs to reconstruct each disputed outcome, including AI actions. For Reg E error resolution, keep an exportable, timestamped record of:
Notice receipt and the consumer’s original allegation.
Evidence reviewed and investigation steps taken.
The determination, its rationale, and reviewer approval.
Credits, reversals, and notices sent.
Attach the case ID, policy version, source record, and system result to each AI action, a baseline for AI support platforms for compliance-heavy fintech. Aggregate activity logs leave gaps. Require attribution for each resolution so reviewers can trace the outcome back to its evidence.
Where AI fits in the Reg E workflow
Set AI permissions by Reg E workflow stage. Separate permission to send messages from authority to decide outcomes:
First contact: capture the consumer’s notice and create the case.
Investigation: answer status questions using the case system.
Provisional credit: confirm the credit event before sending approved communications.
Case closure: send result notifications only after approval.
Keep investigation determinations and adverse findings that trigger consumer rights with a human decision-maker. When the case system lacks a confirmed result, route the communication for review before sending. The same gating logic applies when AI auto-approves credit limit increases in Freshdesk.
Fini's autonomous agent in compliance-focused fintech support
Resolution Rate 90%. Live in 14 days, fully autonomous in 30.
3M+ monthly resolutions across fintech and healthcare. This guide focuses on the fintech portion of that total.
Voice, chat, and email share policies and audit trails.
Guardrails check policy compliance, allowed URLs, and confidential data.
Escalations carry context.
Before launching Reg E error resolution AI workflows, validate intake and deadline controls. For the intake side, see how AI agents handle charge disputes from intake to resolution.
Our posture: SOC 2 Type II · ISO 27001:2022 · PCI DSS Level 1 · HIPAA-compliant · BAA-eligible · GDPR · CCPA.
Pricing starts at $0.49 per resolution. No per-seat fees.
90-Day Money-Back Guarantee: 90% resolution in 90 days, or you pay $0.
Final thoughts on Reg E dispute automation
A missed deadline can undo the value of faster intake. You need a record of every notice, credit, and decision in your workflow. Read the Atlas story.
FAQ
Should you launch Fini on all disputes?
Start with a limited set of dispute intake and status requests, with human investigators retaining decision authority. Expand only after your compliance team approves test results for notice timestamps, deadline tracking, escalation, and customer communications.
Can you use Fini for chargebacks too?
Scope Fini’s role to intake and approved communications, with separate routing for card-network chargebacks and Reg E investigations. A chargeback process does not replace Reg E duties, so your workflow must track each applicable deadline and review path independently.
How do you test Fini before launch?
Run sample cases through your proposed Reg E error resolution AI workflow, including incomplete oral notices, authorized transfers with incorrect amounts, and unconfirmed credit events. Check that Fini preserves the original notice date, routes disputed findings for human review, and never reports a credit without system confirmation. Test connected-system actions separately from knowledge-based responses.
Related guides
Explore the guide topics to find more reading.
Co-founder